Tracing Supply Chain Shifts Triggered by Rapid AI Progress in Computing Hardware
Written by Quinn Lange · Oct 30, 2026
Tracing Supply Chain Shifts Triggered by Rapid AI Progress in Computing Hardware
AI model training and inference workloads have driven sustained demand for specialized accelerators, graphics processors, and high-bandwidth memory modules since the early 2020s, and those requirements continue to intersect with manufacturing capacity originally allocated to general-purpose CPUs, DRAM, and storage components. Production lines that once balanced output across consumer laptops, enterprise servers, and embedded systems now allocate increasing wafer starts toward AI-optimized dies, which in turn alters allocation schedules for legacy part numbers.
Shifts in Semiconductor Fabrication Priorities
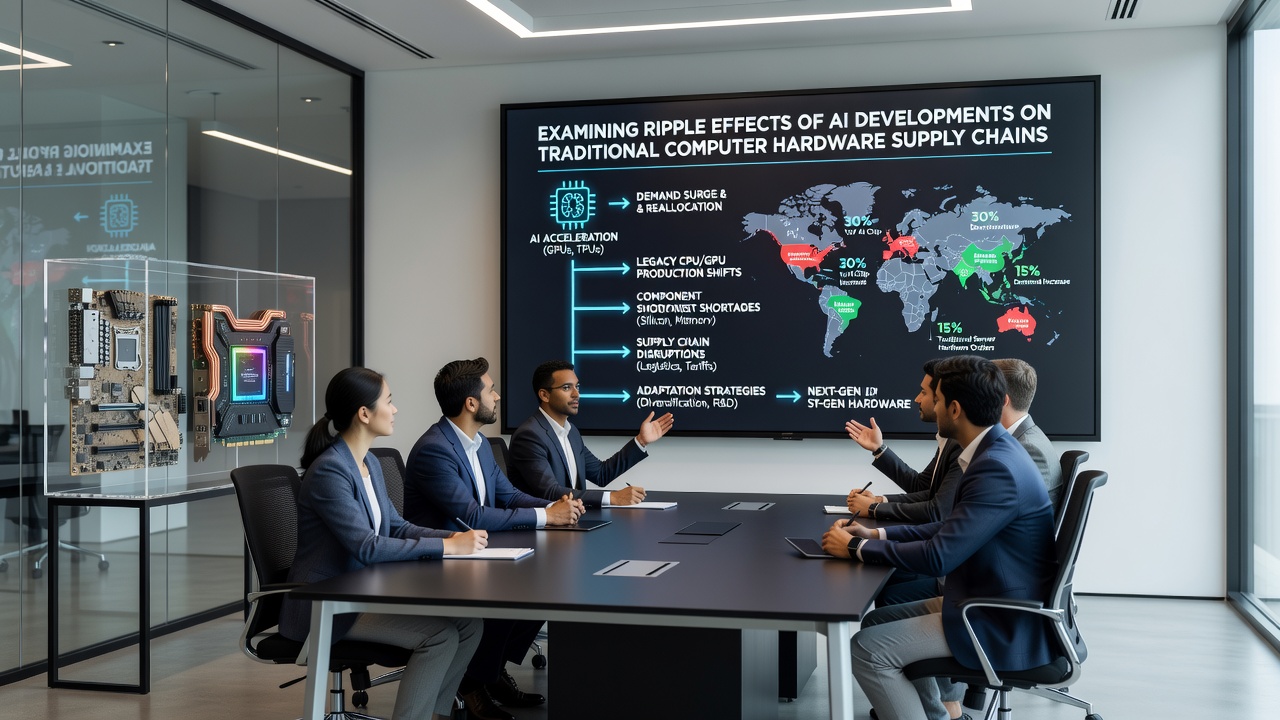
Foundries operating at advanced nodes report that AI-specific chips often require larger die sizes and additional mask layers, extending cycle times and reducing the number of wafers available for conventional processors in the same period. Data from industry tracking services show that capacity reservations for AI accelerators grew from roughly 15 percent of leading-edge output in 2023 to over 35 percent by mid-2026, leaving reduced headroom for updates to x86 and ARM-based CPUs used in traditional desktops and notebooks. Equipment vendors note that extreme ultraviolet lithography tools remain the primary bottleneck, and those tools are frequently booked months ahead for the highest-margin AI products.
Effects on Memory and Storage Component Flows
High-bandwidth memory stacks paired with AI accelerators consume significant quantities of DRAM dies that previously supplied server DIMMs and graphics cards, and this reallocation has produced measurable lead-time extensions for standard DDR5 modules in several quarters. Storage suppliers similarly observe that solid-state drive controllers designed for data-center caching now compete for the same NAND flash wafers used in consumer SSDs, prompting some manufacturers to delay refreshes of older product lines. Observers note that these reallocations appear most pronounced in facilities located in Taiwan and South Korea, where contract terms increasingly favor high-volume AI customers.
Logistics and Inventory Adjustments Across Regions
Distributors in North America and Europe report tighter allocations for older-generation server boards and add-in cards as component lots are redirected toward new AI server configurations, and this pattern has encouraged some system integrators to extend support cycles for existing hardware rather than introduce refreshed models. In October 2026, customs data from several Asian export hubs indicated continued growth in shipments of AI-related substrates and interposers, while volumes for conventional motherboard components remained flat or declined slightly compared with the prior year. Those figures align with statements from the Semiconductor Industry Association regarding capacity utilization rates at major foundries.
Responses from Equipment and Materials Suppliers
Suppliers of photoresists, specialty gases, and silicon wafers have adjusted long-term contracts to accommodate the higher consumption rates associated with AI chip production, and this adjustment has occasionally created spot shortages for materials used in mature-node processes that still support automotive and industrial controllers. Research groups at several universities have documented how these material shifts propagate downstream, lengthening qualification timelines for new designs that rely on older process technologies. Government agencies in the United States and the European Union have published updates on critical materials monitoring programs that track these same flows.
Case Examples from Industry Segments
One contract manufacturer serving both cloud providers and traditional PC brands described reallocating surface-mount lines to prioritize GPU modules, which delayed shipments of certain workstation motherboards by several weeks during peak periods. Another firm specializing in embedded systems reported extending the lifecycle of existing designs because newer components faced longer procurement cycles. These examples illustrate how capacity decisions at the front end of the supply chain reach multiple end markets simultaneously.
Conclusion
Capacity planning documents released by major foundries and memory producers indicate that AI-related demand will remain a significant share of advanced-node output through at least 2027, and traditional hardware categories will continue to operate within the remaining allocation windows. Monitoring reports from industry associations and regulatory bodies in multiple regions provide ongoing visibility into these dynamics, allowing participants across the supply chain to adjust forecasting models accordingly.